Summary: From a fundamental perspective, we remain positive on the long-term trend. In the short term, however, with large overseas warehouse deliveries before the National Day holiday, global inventories have stopped falling and rebounded. Strong supply and demand are both putting some pressure on copper prices. Still, global inventories remain at historically low levels, providing support for absolute prices, so copper prices are expected to move within a range.
Key points: On October 12, Shanghai electrolytic copper spot prices were quoted at a premium of 140-210 yuan/t over the current-month contract. Guangdong electrolytic copper spot was quoted at a discount of 30 yuan/t to a premium of 80 yuan/t, while SX-EW copper was quoted at a discount of 70-80 yuan/t. Sellers were active in selling, premiums kept moving lower, and downstream companies replenished moderately at low prices. Overall trading was moderate.
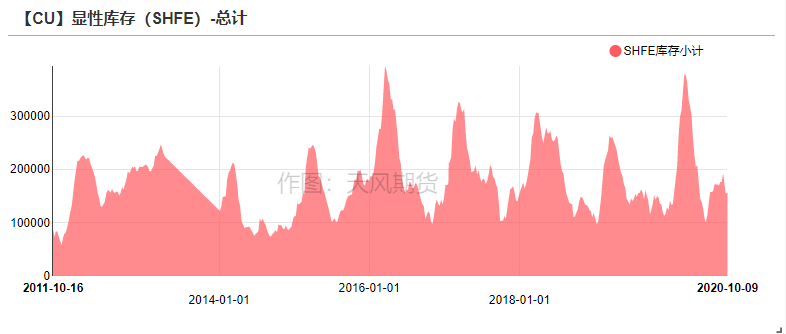
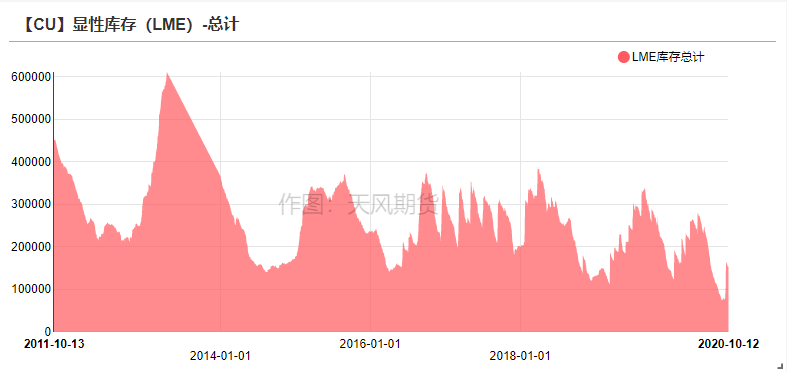
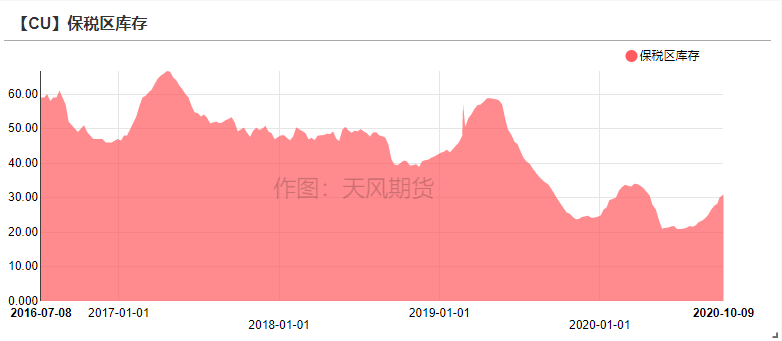
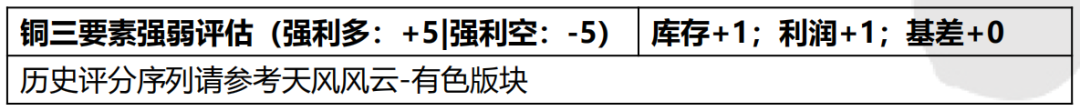
During the National Day holiday, global visible inventories declined slightly by 11,000 tons to 602,600 tons. Among them, LME inventories fell by 11,600 tons to 153,900 tons, COMEX inventories fell by 1,000 tons to 78,000 tons, bonded-zone inventories were basically flat, and SHFE inventories increased slightly by 1,000 tons to 156,000 tons.
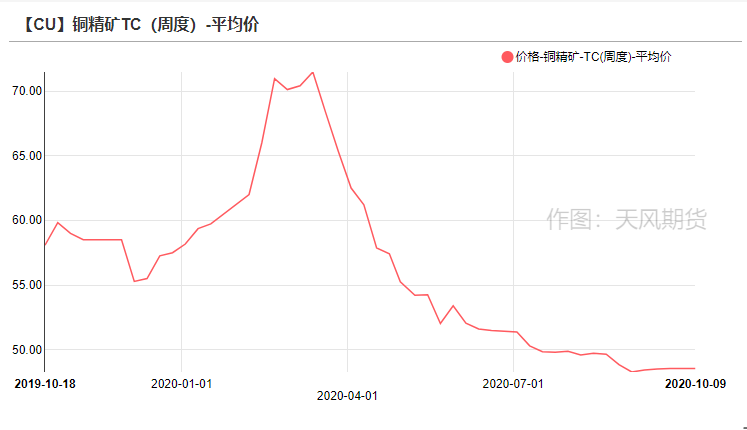
Copper concentrate TC remains at historical lows, with limited short-term rebound potential, and copper smelters' profitability has not improved.
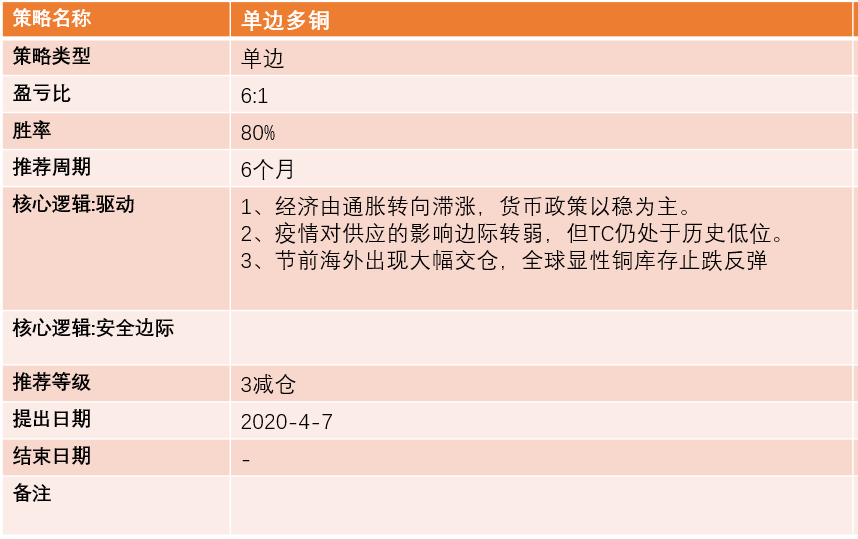
Operation suggestion and logic: Reduce positions. From a macro perspective, policy is unlikely to maintain sustained support in the short term and can only focus on stability. From a fundamental perspective, we remain positive on the long-term trend. In the short term, however, with large overseas warehouse deliveries before the National Day holiday, global inventories have stopped falling and rebounded. Strong supply and demand are both putting some pressure on copper prices. Still, global inventories remain at historically low levels, providing support for absolute prices, so copper prices are expected to move within a range.
Key focus: 1. Domestic consumption. 2. Pace of overseas economic recovery. 3. Latest developments in the overseas epidemic.
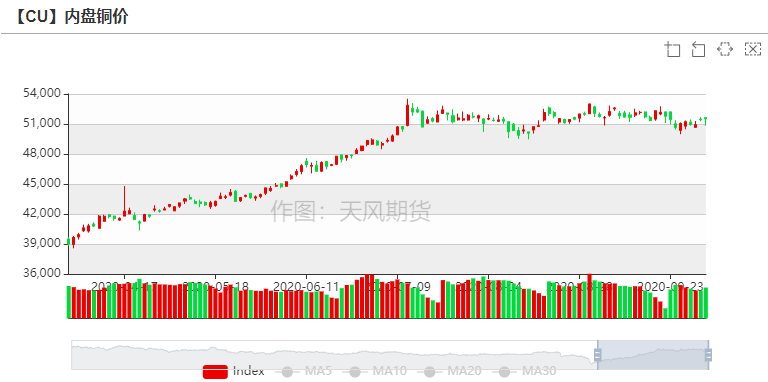
Last week's market review: Volatility declined, and copper prices continued to consolidate in a narrow range. Copper prices remained range-bound at high levels. In the week before and after the holiday, copper prices consolidated between 50,470 yuan/t and 51,680 yuan/t, closing at 51,440 yuan/t, up 0.8%.
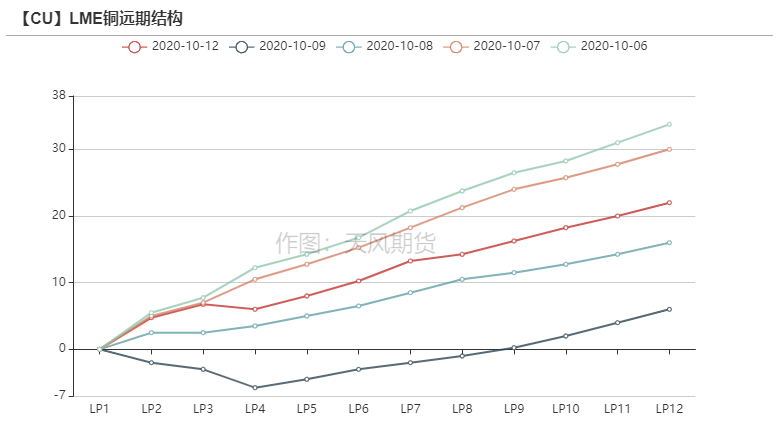
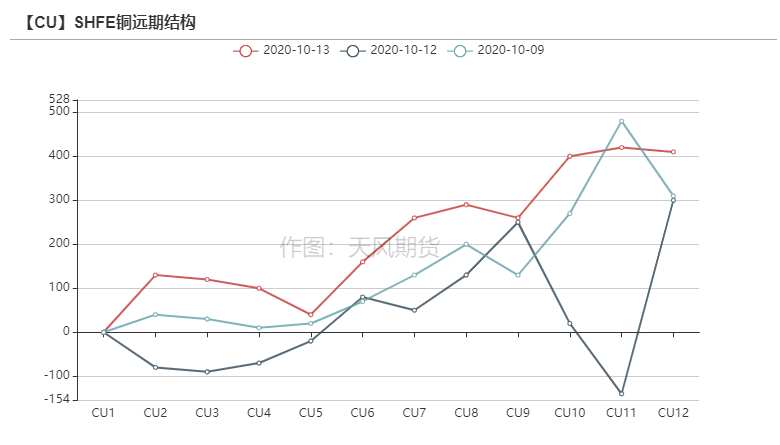
With large overseas warehouse deliveries before the holiday, the LME structure shifted from backwardation to contango. Domestic inventories increased slightly during the National Day holiday, and the contango was maintained.
Source: WIND, Tianfeng Futures Research Institute.
TC stabilizes, mine-side trading thin?
Copper concentrate TC remains at low levels. On October 9, the SMM copper concentrate index was reported at $48.56/t. The spot market remained deadlocked, with relatively light trading.
On the news front, the CSPT group held its latest Q4 floor price meeting on the morning of September 29 and set the Q4 TC/RC floor price at $58/t and 5.8 cents/lb, up $5/t and 0.5 cents/lb from the Q3 floor price. Domestic smelters currently have relatively sufficient stockpiles, and many have brought forward their Q4 and Q1 stockpiling demand, leading to a notable rise in the Q4 floor price.
Source: SMM, Tianfeng Futures Research Institute.
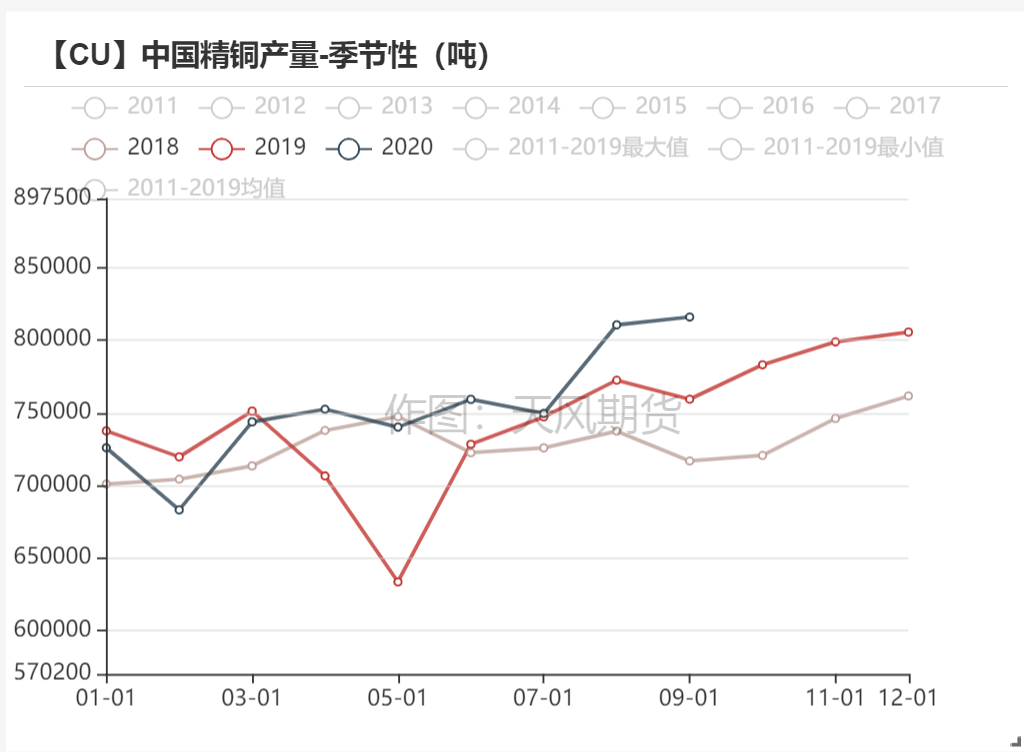
Refined copper production remained high in September. According to SMM, China's electrolytic copper production in September was 809,800 tons, down 0.09% month-on-month and up 6.65% year-on-year. Cumulative production from January to September was 6.8042 million tons, up 3.76% year-on-year.
Domestic electrolytic copper output remained at a relatively high level in September, mainly because some large smelters were catching up on annual production plans. Copper concentrate imports also rebounded sharply in September, so operating rates at large smelters rose further. However, as domestic scrap copper supply became tighter and the refined-scrap spread narrowed, smelters using blister copper and scrap saw lower output in September than in August. As a result, overall domestic electrolytic copper production was roughly flat month-on-month.
Entering October, with some smelters recovering from maintenance and new capacity coming on stream, domestic electrolytic copper production is expected to increase slightly.
In addition, China's refined copper imports remained high in September. Imports of unwrought copper and copper products were 722,000 tons, up 60% year-on-year and 8% month-on-month, compared with 668,000 tons in August.
Source: Tianfeng Fengyun, SMM.
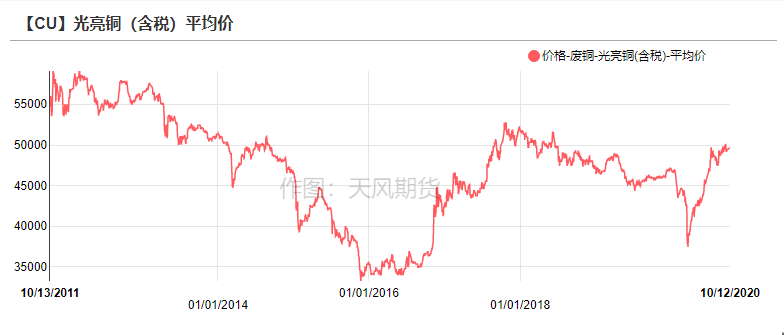
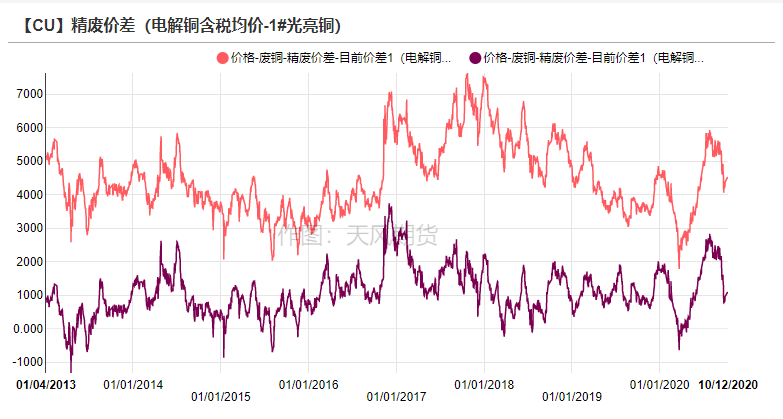
Electrolytic copper prices fell, and the refined-scrap spread continued to narrow. Before the holiday, the weekly average price of No.1 bright copper was 50,232 yuan/t including tax and 46,155 yuan/t excluding tax. The refined-scrap spread continued to weaken to around 879 yuan/t.
With scrap copper inventories largely released in June-July, domestic scrap copper supply tightened again from August, and quotes remained relatively firm. As copper prices corrected before the holiday, the refined-scrap spread quickly narrowed to below 1,000 yuan/t.
At present, the maximum Q4 quota has been issued, with a total of 136,400 tons, lower than the maximum Q3 quota. The detailed implementation rules for the recycled copper policy have not yet been introduced. In addition, the new Solid Waste Law has to some extent inhibited scrap copper transport, so the increase in Q4 scrap copper imports is expected to be limited.
Source: Tianfeng Fengyun, SMM.
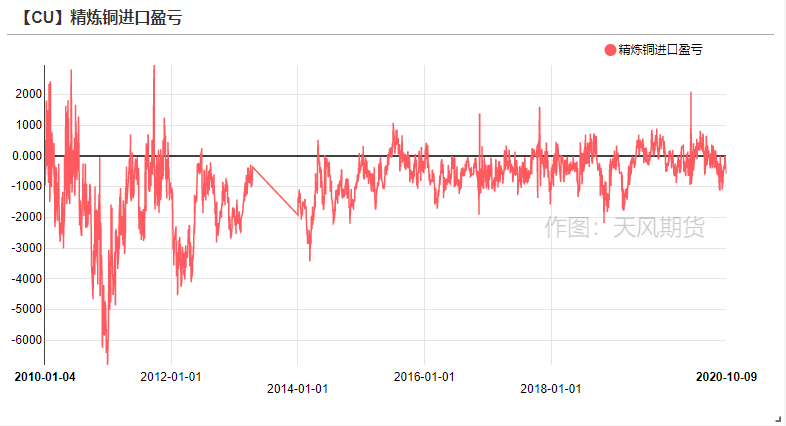
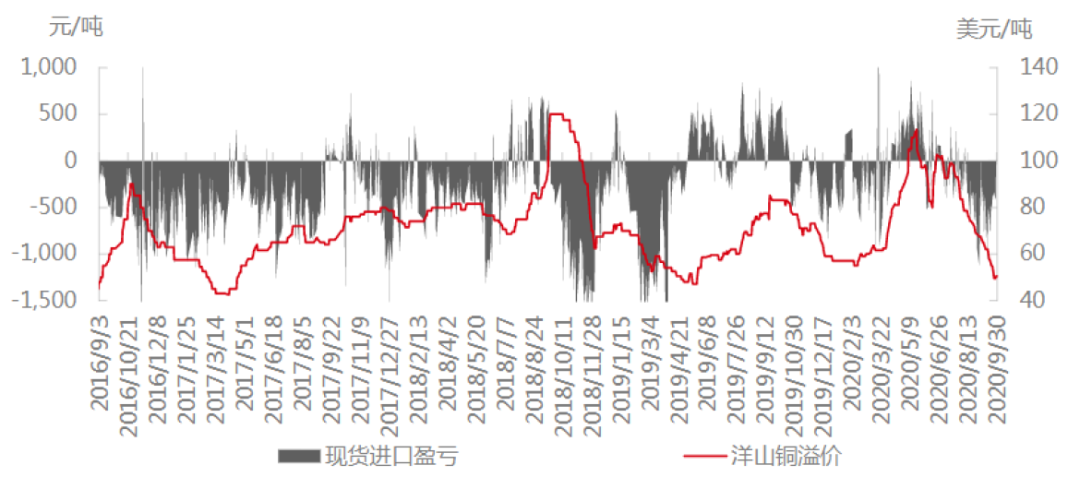
The import window remained closed, and Yangshan copper trading was thin.
[CU] Refined copper import profit/loss & Yangshan copper premium (yuan/t)
Source: SMM, Tianfeng Futures Research Institute.
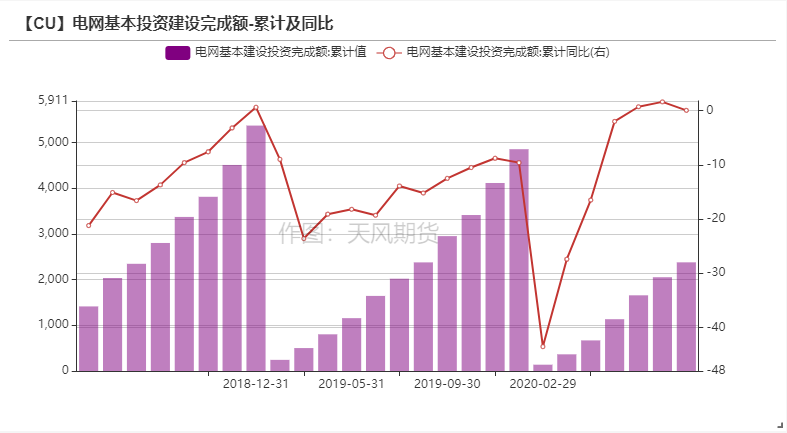
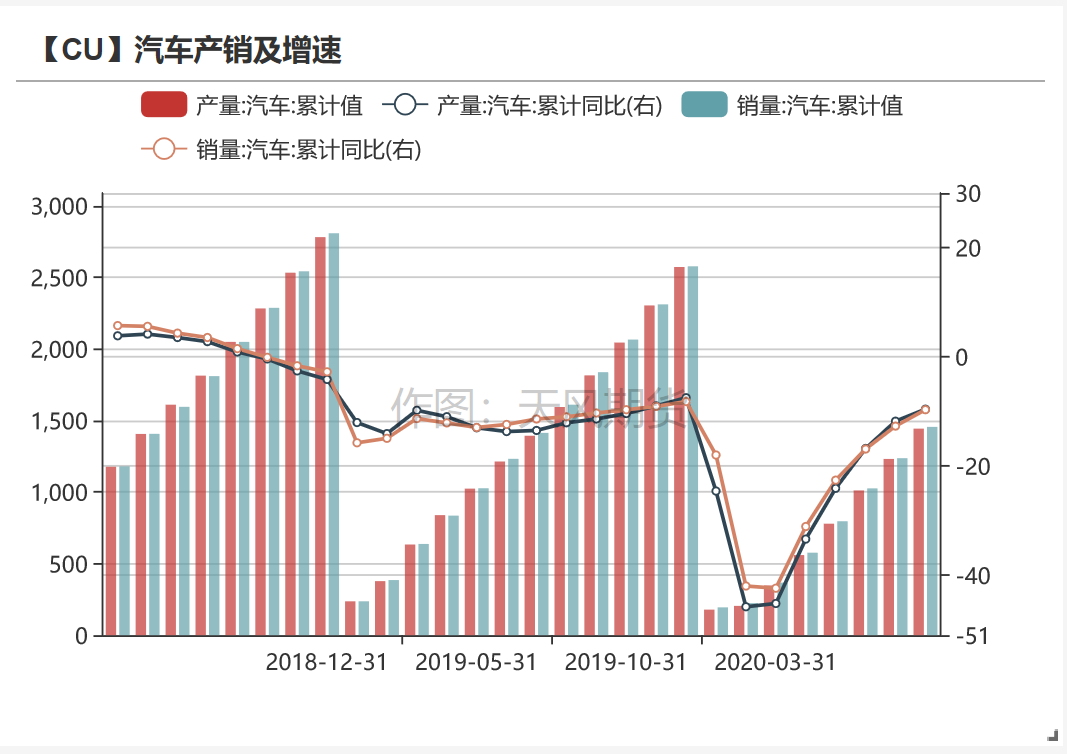
Terminal demand continues its rebound trend.
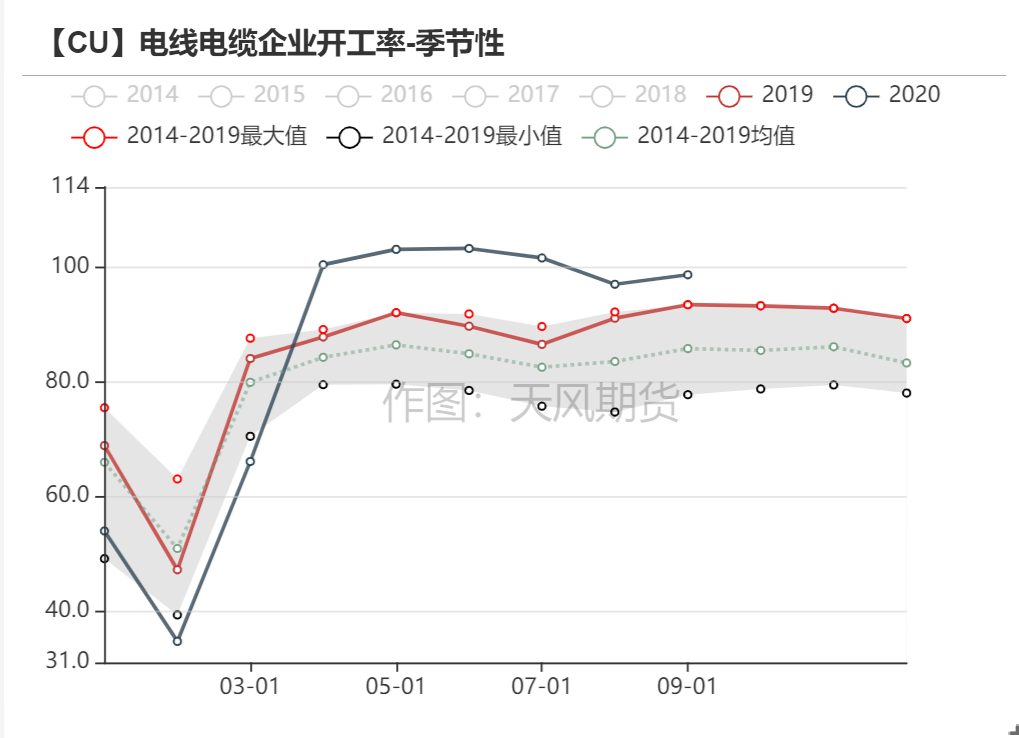
Wire and cable company operating rates remained high in September. The wire and cable operating rate in September was 96.03%, down 0.99 percentage points month-on-month and up 2.58 percentage points year-on-year.
We believe that although September wire and cable operating rates fell slightly month-on-month, they remain at an absolute high, and the consumption peak season has not been disproven.
Source: SMM.
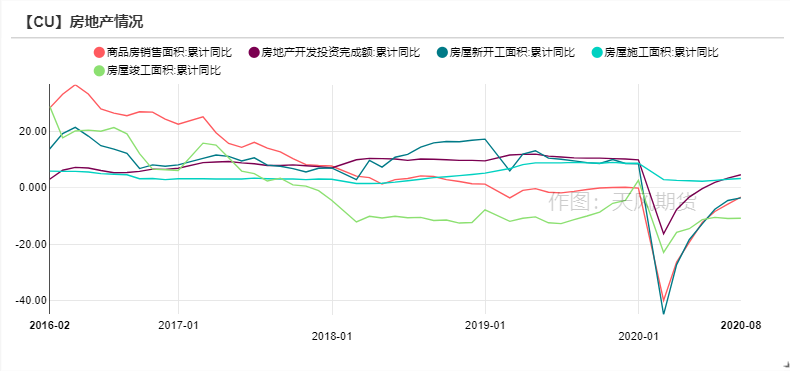
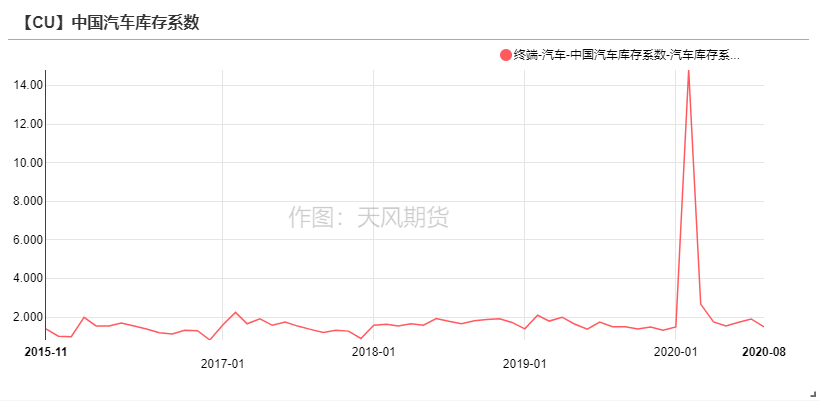
Terminal consumption continues to rebound.
Source: Tianfeng Fengyun.
Global inventories remain at absolute lows.
Large overseas warehouse deliveries before the holiday, slight destocking during National Day. During the National Day holiday, global visible inventories declined slightly by 11,000 tons to 602,600 tons. Among them, LME inventories fell by 11,600 tons to 153,900 tons, COMEX inventories fell by 1,000 tons to 78,000 tons, bonded-zone inventories were basically flat, and SHFE inventories increased slightly by 1,000 tons to 156,000 tons.
Source: Wind, Bloomberg, Tianfeng Futures Research Institute.
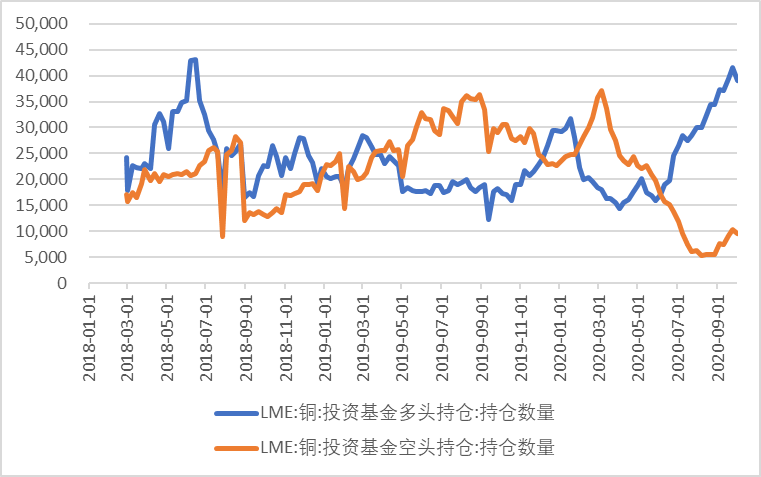
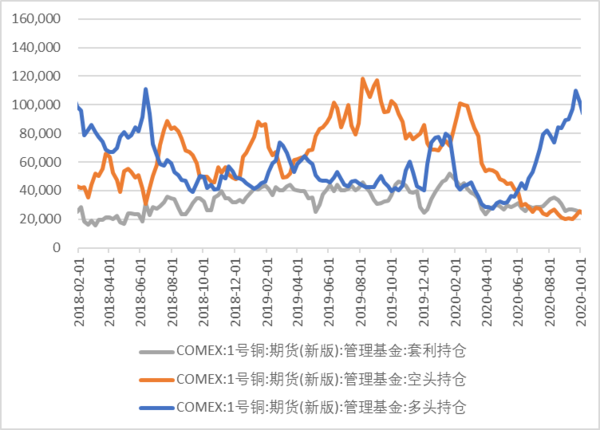
Investment fund long positions remain at high levels.
[CU] LME institutional positioning
[CU] COMEX institutional positioning